Think Housing is Your Biggest Expense? Think Again!
Anita Groves • September 26, 2017

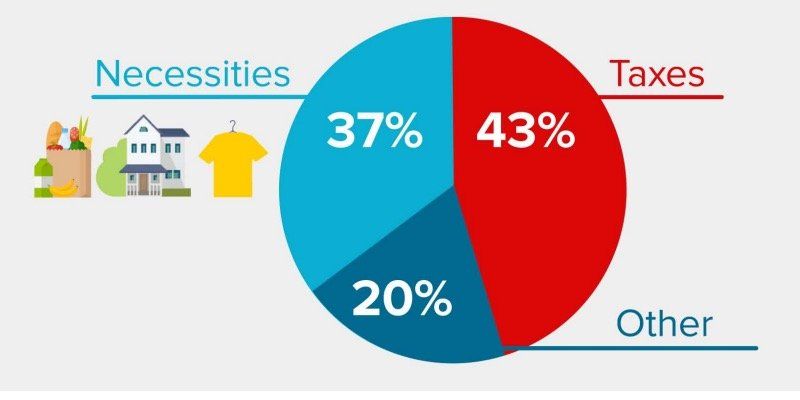
Oftentimes people assume that housing is our single biggest expense, and although that was true in 1961, times have changed! According to research done by the Fraser Institute, last year the average Canadian family spent more on taxes than housing, food, and clothing combined. Here is the news release from the Fraser Institute along with a copy of the report.


Now although I might not be able to help you reduce the amount of taxes you pay, if you would like to review your mortgage to see if you can save any money there, please don’t hesitate to contact me anytime!


NEWS RELEASE

Taxes—not housing and basic necessities—are largest Canadian household expense.

Despite high housing costs across the country, the average Canadian family spent more on taxes in 2016 than housing, food and clothing combined, finds a new study released today by the Fraser Institute, an independent, non-partisan Canadian public policy think-tank.

“Many Canadians may think housing is their biggest household expense, but in fact the average Canadian family spent more on taxes last year than on life’s basic necessities—including housing,” said Charles Lammam, director of fiscal studies at the Fraser Institute and co-author of the Canadian Consumer Tax Index, which tracked the total tax bill of the average Canadian family from 1961 to 2016.

Last year, the average Canadian family earned $83,105 and paid $35,283 in total taxes compared to $31,069 on housing (including rent and mortgage payments), food and clothing combined.

In fact, the average Canadian family paid nearly twice as much of their income in taxes (42.5 per cent) as they did for housing (22.1 per cent). The basic necessities of life, which include food, clothing and housing, amounted to just 37.4 per cent of income—still less than the percentage of income going to taxes.

This represents a marked shift since 1961, when the average Canadian family spent much less on taxes (33.5 per cent) than on food, clothing and housing (56.5 per cent).

The total tax bill reflects both visible and hidden taxes that families pay to the federal, provincial and local governments including income, payroll, sales, property, carbon, health, fuel and alcohol taxes and more.

Since 1961, the average Canadian family’s total tax bill has increased by a staggering 2,006 per cent, dwarfing increases in annual housing costs (1,527 per cent), clothing (677 per cent), and food (639 per cent).

Even after accounting for inflation, the tax bill has still increased 157.6 per cent over this period.

“Taxes help fund important public services that Canadians rely on, but the issue is the amount of taxes governments take compared to what Canadians get in return,” Lammam said.

“With more than 42 per cent of their income going to taxes, Canadians might ask whether they’re getting good value for their tax dollars.”

Share
Kevin Roye

PROFESSIONAL MORTGAGE BROKER
CONTACT ME APPLY NOW

Download My Mortgage App HERE

Recent Posts


Small-business owner reviewing financial paperwork at a workshop desk.
By Kevin Roye • November 16, 2026
Self-employed with seasonal income? Learn which records to organize before a mortgage application in Orillia and how to explain changing business cash flow.
By Kevin Roye • November 11, 2026
What Lenders Mean by “Good Credit” When You Apply for a Mortgage Credit is simply the ability to borrow money today based on the trust that you’ll repay it in the future. When you apply for a mortgage, lenders want proof that you’ve consistently honoured that trust by managing credit responsibly. But what does a good credit history actually look like to a lender? The 2 / 2 / 2 Rule Explained If you’re newer to credit or want a simple way to remember minimum mortgage credit requirements, think of the 2 / 2 / 2 rule: 2 active trade lines Established for at least 2 years With a minimum combined limit of $2,000 This is a common baseline lenders use when assessing credit for mortgage financing. What Counts as a Trade Line? A trade line is any account where credit is extended to you, such as: A credit card A line of credit A car loan A personal or installment loan Each trade line reports your payment history to the credit bureau and contributes to your credit score. For a trade line to be considered active , it must: Have been used at least once, and Show activity at least once every three months Why Time Matters Lenders want to see that you’ve managed credit responsibly over time , not just recently. Using two trade lines consistently for at least two years helps demonstrate stable financial habits and reliability. Understanding Credit Limits vs. Balances The credit limit is what matters—not the balance. For example: A $1,000 credit card + a $2,500 line of credit = $3,500 total limit This meets the minimum requirement You do not need to carry a balance to build credit. In fact, the best approach is to: Use your credit regularly Pay it off in full each month (for credit cards) Make all loan payments on time If your lender offers a credit limit increase and you’re managing credit well, it’s often a good idea to accept it. Higher limits—used responsibly—can strengthen your credit profile. A Simple Way to Build Credit Automatically One effective strategy is to: Put recurring bills on your credit card Set up an automatic transfer to pay the balance in full every month Automation helps build positive credit history without requiring constant attention—just be sure to monitor your accounts to ensure everything runs smoothly. What About Credit Scores? Yes, credit scores matter—but they’re not the whole story. If you: Have two active trade lines Established for two years With at least $2,000 in total limits And no missed payments …your credit score will generally take care of itself. That said, it’s still wise to review your credit report occasionally to check for errors or unfamiliar accounts. Final Thoughts If you’re thinking about buying a home in the next couple of years, now is the perfect time to review your credit and make sure you’re on track. Small adjustments today can make a big difference when it’s time to apply for a mortgage. If you’d like help reviewing your credit or understanding how it affects your mortgage options, feel free to connect anytime. I’d be happy to walk through it with you and help you plan with confidence.